You arrive, unpack, enjoy the peace and quiet, and then head home, leaving everything in the good hands of your local managers and trusted contacts until you return.
For owners of high value luxury homes in Virgin Gorda, that time away creates an important question: Does your property insurance still reflect the home you own today?
Renovations, imported furnishings, upgraded equipment and rising rebuilding costs can change the value at risk. A policy arranged several years ago may no longer match the property, even when it has renewed without interruption.
Luxury properties need a more detailed coverage review
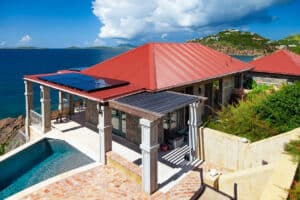
Virgin Gorda has one of the BVI’s strongest concentrations of luxury and internationally owned property. Homes at this level often include features that require careful consideration:
- Custom construction and specialist finishes
- Imported furniture, artwork and appliances
- Pools, generators and solar equipment
- Detached guest accommodation
- Landscaping, retaining walls, docks or other external structures
- Property management and short-term rental arrangements
Standard property valuations often fail to reflect the full cost of rebuilding to luxury standards after a major loss. A home’s market purchase price can differ significantly from its actual rebuilding cost.
Start with how the property is actually used
Occupancy affects risk. If your Virgin Gorda home remains vacant for extended periods, your insurer may need details about inspections, security, maintenance and storm preparation.
If the property is rented while you’re overseas, the policy should accurately record that use. A home used exclusively by its owner presents a different risk from one occupied by paying guests.
Your review should confirm:
- Whether the property is a primary, secondary or rental residence
- How long it may remain unoccupied
- Who inspects it in your absence
- How hurricane shutters and outdoor items are managed
- Whether renovations or structural changes have been declared
- Whether building and contents values remain accurate
Small administrative gaps can become serious complications when a claim is submitted.
Your BVI property must be insured through a licensed provider
The BVI Insurance Act 2008 treats insurance of physical real estate situated in the British Virgin Islands as domestic business. This means the policy covering your BVI property must be written through an insurer authorised by the BVI Financial Services Commission (FSC).
International insurance markets may participate through reinsurance, fronting arrangements or local general agents. However, the policy must be issued through an appropriately licensed BVI entity.
If your property is mortgaged through a local bank, the lender will usually require property insurance from an approved, locally licensed provider. Requirements commonly include protection for risks such as hurricane, windstorm, flood and fire, subject to the policy’s wording, exclusions, limits and deductibles.
Before placing or renewing coverage, confirm:
- The issuing insurer is licensed for the relevant business in the BVI.
- Your lender’s requirements are reflected in the policy.
- The insured values are supported by an up-to-date professional valuation.
- The coverage, limits, exclusions and deductibles are clearly understood.
Review the details before hurricane conditions develop
A hurricane deductible may be calculated as a percentage of the insured value. On a $2 million property, even a modest percentage represents a substantial amount.
Owners should also review how the policy addresses windstorm, flood, contents, debris removal, temporary accommodation and rental income, where applicable. Coverage varies, so the policy wording matters.
Timing matters too. Insurers may restrict new policies or material changes when a named storm is approaching the territory. Waiting until a system appears on the forecast can leave little room to adjust values or resolve missing information.
Keep the documentation close, even when you’re far away
A simple digital property file can make reviews and claims more efficient. Include:
- Current property valuation
- Recent photographs and video
- Contents inventory with receipts where available
- Renovation records and contractor invoices
- Property manager and emergency contact details
- Policy schedule and wording
- Mortgage documentation
- Maintenance and inspection records
Ask your property manager to update photographs periodically, particularly after renovations or major purchases. Clear documentation helps establish what was present and its condition before an event.
Book your complimentary Hurricane Coverage Check
Yes, we’re helping BVI property owners review the details that can easily fall out of date.
Our complimentary Hurricane Coverage Check is a focused 15-minute review by phone, email, WhatsApp or in our office. We’ll ask about your property’s use, building and contents values, recent renovations, equipment purchases, renewal timing and preferred follow-up.
Keep in mind that a review identifies information that may need updating. It’s not a promise of coverage.
To arrange your complimentary Hurricane Coverage Check, WhatsApp “COVER” to 284-495-6800 or fill out the form below.
A luxury property deserves more than an automatic renewal. It deserves a current, accurate review of what you’ve built and what it could take to restore it.
Request Your Property Insurance Quote Today!
Share a few details below, and a BVI-based advisor from Premier Insurance will contact you within 24 hours.